October 2026 Portland Metro Real Estate Market Update: Rates Climb, Buyers Pause
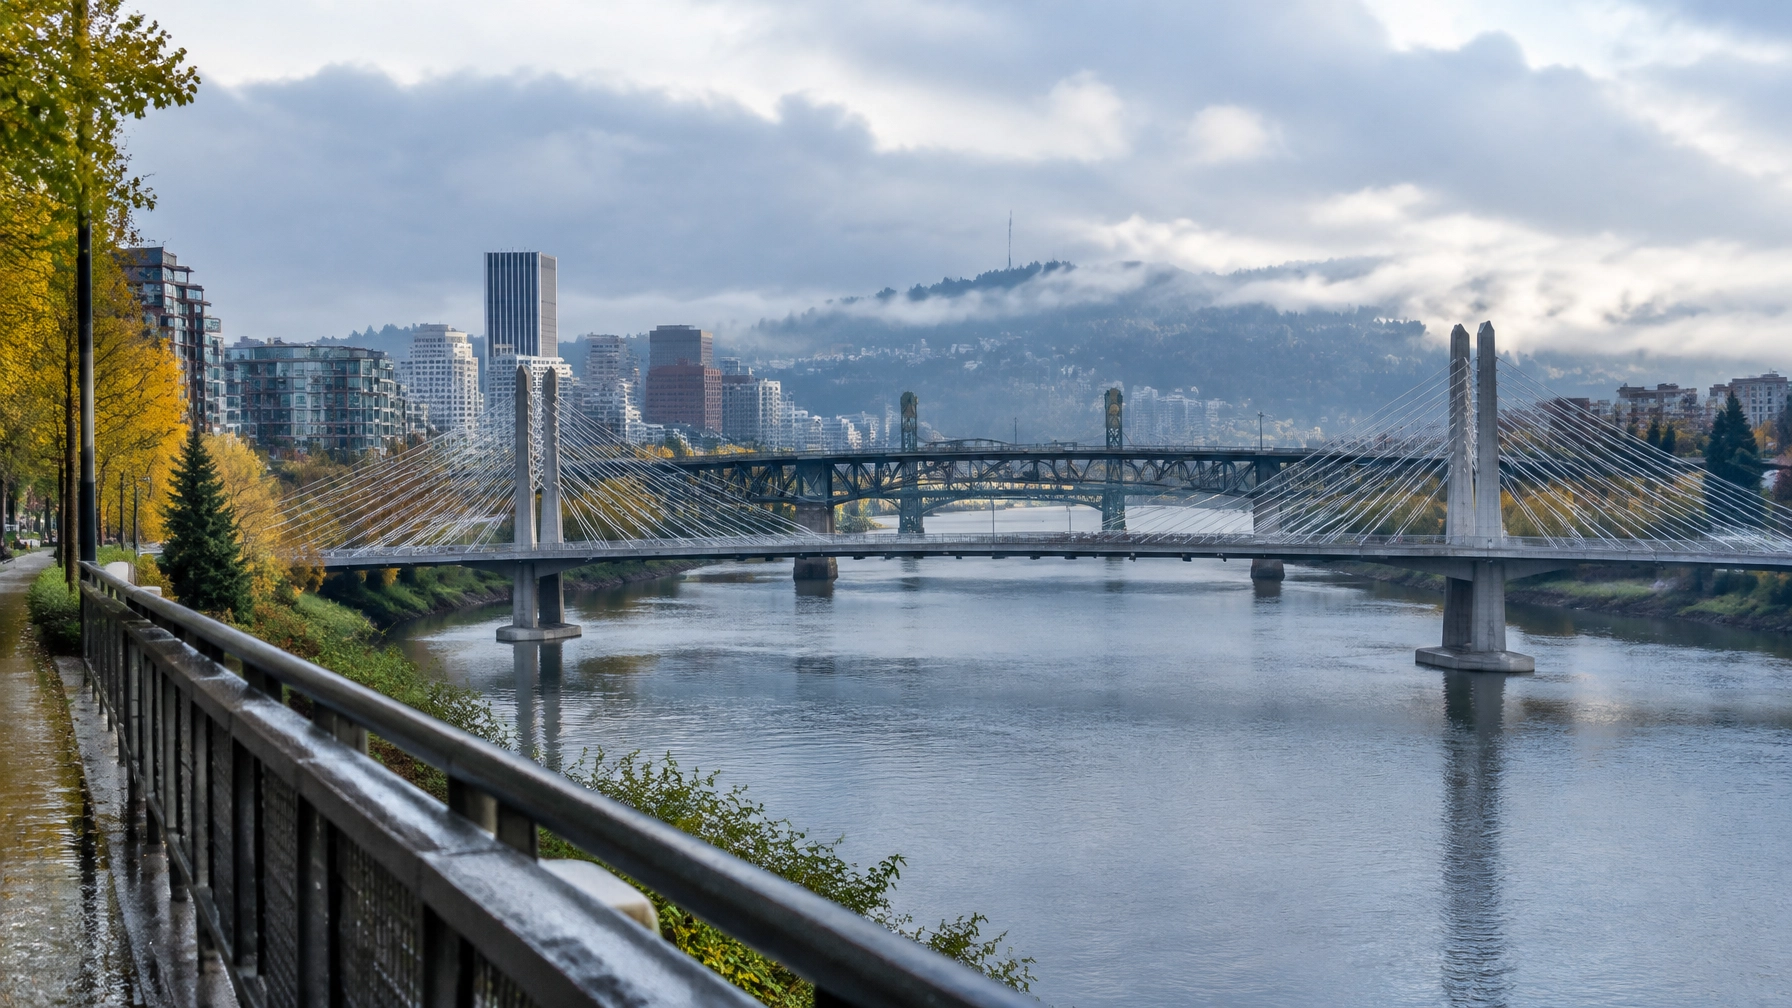
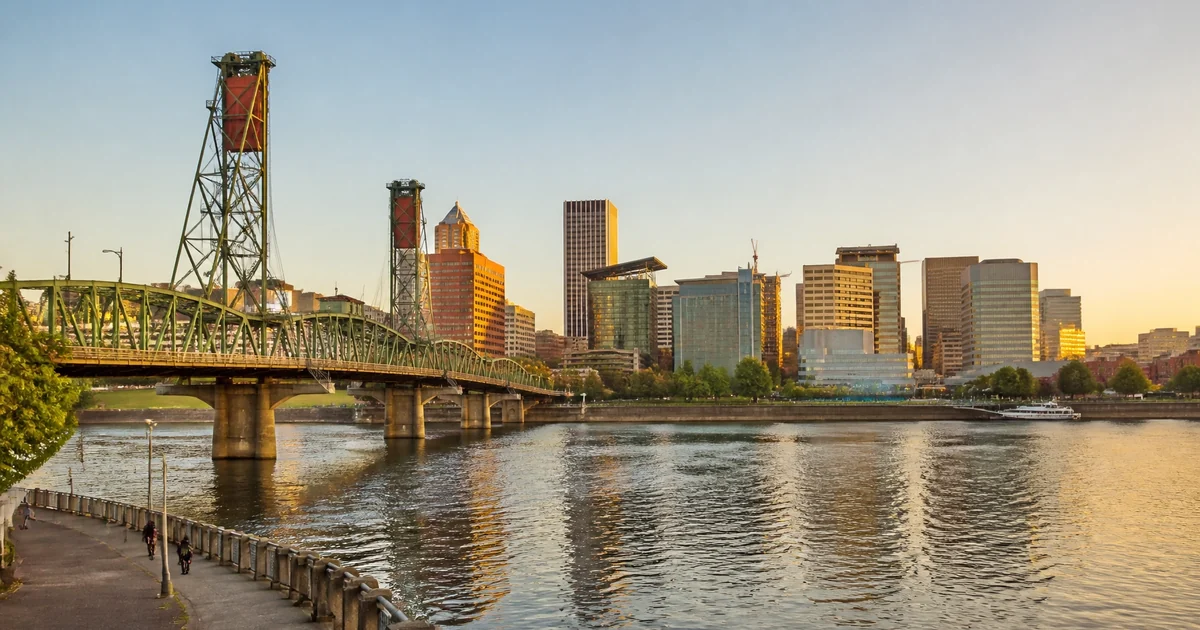
Tilikum Crossing and the Willamette River in Portland as fall arrives, and with it a market that has shifted into a slower, more deliberate season.
In September 2026, Portland Metro pending sales fell 17.9% year over year to 1,760, the fewest September contracts since 2010, as 30-year mortgage rates climbed past 7%. The median sale price held flat at $545,000 while inventory rose to 4.2 months. Buyers gained choice and time; higher payments are the main headwind.
If you watched mortgage rates in September, you already know the story. The 30-year fixed started the month at 6.71%, crossed 7% on September 24, and reached 7.28% on October 1, the highest level since October 2023. In between, the Federal Reserve raised its benchmark rate for the first time since 2023. Portland Metro buyers felt every step of that climb.
Here is what the September RMLS Market Action Report shows. The median sale price was $545,000, exactly where it stood last September. Inventory rose to 4.2 months from 3.8 a year ago. Closed sales fell 4.0% to 1,752, and total market time stretched to 68 days, six days longer than last September and eleven longer than August.
The number that matters most is pending sales: 1,760 contracts, down 17.9%. Prices have not moved. Activity has. So what does that mean for you this fall?
- Pending sales fell 17.9% to 1,760, the fewest September contracts since 2010
- Lockbox showings dropped 15.7% to 55,625, the lowest September on record
- The same $545,000 median home now costs about $147 more per month than a year ago
- Buyers have 4.2 months of inventory, the most choice of any September since 2012
- The median held at $545,000, so well-priced homes are still selling
- 14 of 15 Portland Metro sub-markets had fewer pending sales than last year
- The Fed's first rate hike since 2023 points to a cautious fall
Market Overview: Rates Rose, Contracts Fell, Prices Held
September's headline is the gap between price and activity. The median sale price was $545,000, unchanged from a year ago and up 0.9% from August. Meanwhile pending sales fell 12.6% from August and 17.9% from last September. That 1,760 figure is the lowest for any September since 2010.
Inventory tells the other half. Active listings climbed 3.0% in a month to 7,411, the highest count of 2026 and 7.7% above last September. With fewer closings to absorb them, inventory reached 4.2 months, the highest September reading since 2012. This time supply and demand both moved against sellers. You can track the latest figures anytime on our current Portland Metro market data page.
National data points the same direction as RMLS. Realtor.com's September 2026 housing report found 31.6% of Portland listings had a price cut in September, third highest among the 50 largest metros. Rising inventory, slower contracts, and more price reductions line up across sources.
- Inventory: rising, from 3.1 to 4.2 months between June and September 2026
- Pending Sales: falling for five straight months, down 27.8% since May and down 17.9% YoY in September
- Median Price: steady in a $540,000 to $565,000 range since April, down 3.5% from June's $564,900 peak
- Market Time: lengthening, from 54 to 68 days between July and September
Buyer Activity: Showings Hit a September Low
Lockbox data from SentriLock is the earliest signal we have, because a showing comes before an offer. In September, agents opened 55,625 lockboxes across the Portland Metro. That is down 15.7% from last September and down 8.8% from August. It is also the lowest September total in our records, which run back to 2014.
The trend matters more than any single month. Showings ran ahead of 2025 every month from January through May. Since then the gap has widened steadily: -0.8% in June, -6.0% in July, -10.6% in August, and -15.7% in September. Fewer showings now usually mean fewer closings in October and November.
Want to See What's Out There?
With more homes on the market and less competition, this fall gives you room to look carefully. Browse what is available, or reach out and we can talk through what fits.
Affordability: The Rate Did All the Work
At September's average 30-year rate of 6.86% from the Freddie Mac Primary Mortgage Market Survey, with 20% down ($109,000) on the $545,000 median, monthly principal and interest is about $2,861. At October 1's 7.28%, it is about $2,983. Property taxes, homeowners insurance, and maintenance are additional.
Here is the part that stings. Last September the same $545,000 median home at that month's 6.35% average cost about $2,714 a month. Today's buyer pays about $147 more at September's rate and about $270 more at the October 1 rate. The price did not change at all. The rate did all of it.
What This Means for Buyers
If you can handle today's payment comfortably, this fall offers something buyers have not had in years: time and choice. Inventory is at 4.2 months, homes take 68 days on average to go under contract, and sellers are reducing prices more often. You can tour, compare, ask for repairs, and negotiate credits without the pressure of a bidding war on every home.
The key is separating the price from the payment. You can negotiate price with a seller. The rate you largely accept from the market. Many buyers this fall are asking sellers for credits toward closing costs or a rate buydown instead of a lower price, which can do more for the monthly payment.
Buying this fall tends to make the most sense if most of these describe you:
- Your payment at 7% or higher fits your budget with room to spare, before any hoped-for refinance.
- You plan to stay in the home at least five years, giving you time to ride out flat prices.
- Your job and income feel stable through the next 12 months.
- You are pre-approved and ready to negotiate seller credits, repairs, or a rate buydown.
- You are targeting homes that have sat 30 days or more, where sellers are most flexible.
What This Means for Sellers
The good news first. The median price held at $545,000, and homes that are priced right are still selling. The adjustment so far is happening in volume and time, not in price. But fewer buyers are in the market, and each one has more listings to choose from. The first two weeks on the market matter more than ever, because that is when a home gets its strongest attention.
Start by knowing what your home is worth today based on recent closed sales near you, not on spring prices or what a neighbor listed for. If you are thinking about selling this fall, here is the approach that works in this kind of market.
- Price to the market from day one. Chasing the market down with reductions costs more time and money than starting right.
- Invest in presentation. Clean, repaired, well-photographed homes stand out when buyers have 7,411 options.
- Be flexible on terms. A credit toward the buyer's rate buydown can help a buyer more than an equal price cut.
- Watch the first 14 days. If showings are light, adjust early rather than letting the listing go stale.
Sub-Market Spotlight: 14 of 15 Areas Slowed
The slowdown was nearly universal. Fourteen of the 15 Portland Metro sub-markets recorded fewer pending sales than last September. The only exception was Mt. Hood, on just 13 contracts. In July, eight areas were positive. In August, four. Now one. Here are the five areas drawing the most attention this month.
| Area | Median Price (YTD) | YoY Price (YTD) | Closed Sales | YoY Sales | Pending YoY | Market Time |
|---|---|---|---|---|---|---|
| Beaverton/Aloha | $539,500 | -1.9% | 141 | -3.4% | -14.4% | 52 days |
| Hillsboro/Forest Grove | $510,000 | -2.5% | 128 | -19.0% | -30.8% | 68 days |
| Tigard/Wilsonville | $609,000 | -1.3% | 154 | -3.1% | -11.3% | 55 days |
| NE Portland | $525,000 | 0.0% | 144 | -16.3% | -32.9% | 46 days |
| W Portland | $665,000 | +0.8% | 159 | -14.5% | -20.4% | 108 days |
Median prices are year-to-date figures per the RMLS Area Report, compared with the same period in 2025. Closed sales, pending change, and market time are for September 2026 versus September 2025. Prior-year closed sales from RMLS September 2025 Area Report.
Inventory in Months: 2026 So Far
| Month | 2026 Inventory (Months) |
|---|---|
| January | 4.3 |
| February | 3.6 |
| March | 3.0 |
| April | 3.1 |
| May | 3.2 |
| June | 3.1 |
| July | 3.3 |
| August | 3.8 |
| September | 4.2 |
| October | Not yet reported |
| November | Not yet reported |
| December | Not yet reported |
Curious What This Means for Your Home?
Every home and every neighborhood is moving a little differently this fall. A quick valuation shows where yours stands, with no pressure and no obligation.
Looking Ahead: What to Watch This Fall
Mortgage rates and the Fed. The Federal Reserve raised rates on September 16 and its median projection points to one more increase by year end. The September 2026 FOMC statement said inflation "remains elevated." The next meetings are October 27 to 28 and December 8 to 9. As long as the 30-year fixed sits above 7%, expect buyer activity to stay muted.
October and November closings. September's 1,760 pending sales become the closings of the next six weeks. Last October the metro closed 2,066 homes. With pendings this low, a year-over-year decline in fall closings looks likely.
Seasonal inventory. Inventory usually falls in October as fall closings catch up, as it did in both 2024 and 2025. If it holds near 4 months instead, that would confirm buyers have real leverage heading into winter.
Frequently Asked Questions
Is October 2026 a good time to buy a home in Portland? +
How much have Portland home prices changed? +
What does 4.2 months of inventory mean? +
How is the Beaverton and Aloha housing market doing? +
What is happening with home sales in Hillsboro and Forest Grove? +
How do 7% mortgage rates affect Portland buyers? +
Will Portland home prices drop in the rest of 2026? +
Ready to Talk Through Your Next Move?
Whether you are weighing a purchase at today's rates or wondering how to price your home this fall, I am happy to talk it through. No pressure, no obligation.
Homes for Sale in Portland
Browse current listings in Portland.
Market statistics: RMLS Market Action Report, Portland Metro, September 2026 reporting period.
Showing activity: SentriLock lockbox data via RMLS, compiled in the Saling Homes Portland Market Intelligence Tracker.
Mortgage rates: Freddie Mac Primary Mortgage Market Survey and October 1, 2026 release.
Federal Reserve: FOMC statement, September 16, 2026.
Income: HUD median family income, 2026.
Employment: Oregon Employment Department, August 2026.
National: NAR Existing-Home Sales, August 2026; S&P Cotality Case-Shiller, July 2026; NAHB/Wells Fargo HMI, September 2026.
Corroboration: Realtor.com September 2026 Housing Report.
Payment estimates are principal and interest only, 20% down, 30-year fixed, and exclude taxes, insurance, and HOA dues.
Data verified: October 2026
Joe Saling
Real Estate Advisor | Saling Homes at eXp Realty
Joe Saling has been helping Portland-area buyers and sellers for 10 years, backed by 20+ years in sales, marketing, and leadership. He specializes in the Portland Metro market with a focus on data-driven decisions and client education. His approach: educate first, advocate always.
(503) 910-7364 | joe@sellingpdxhomes.com | sellingpdxhomes.com | About Joe
Saling Homes at eXp Realty is committed to equal housing opportunity. We do not discriminate on the basis of race, color, religion, sex, handicap, familial status, or national origin.
Categories
- All Blogs (93)
- Buying a Home (35)
- Community Page (14)
- Downsizing (7)
- Home Buying Process (7)
- Homeownership (6)
- Increasing Your Homes Value (4)
- Local Events (2)
- Market Update (21)
- Mortgage Information (9)
- Neighborhood Eats and Experiences (1)
- neighborhood info (3)
- Real Estate News (15)
- Selling Your Home (20)
Recent Posts
GET MORE INFORMATION